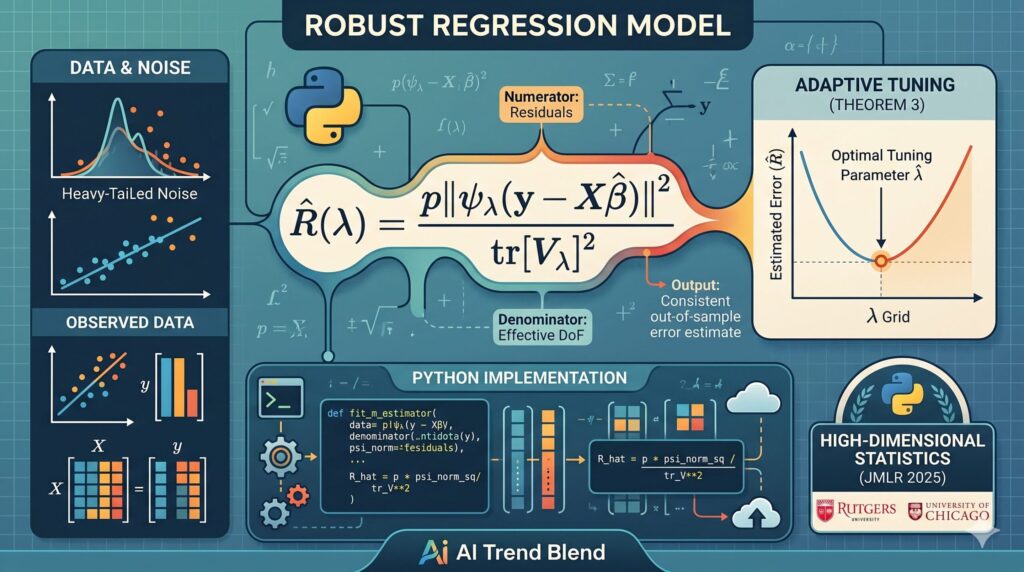
How to Tune a Robust Regression Model Without Knowing the Noise: Adaptive Error Estimation for Unregularized M-Estimators
Pierre C. Bellec (Rutgers) and Takuya Koriyama (Chicago Booth) prove that a simple, fully observable formula consistently estimates the prediction error of any Huber-class M-estimator in high dimensions — and that minimizing it over a grid of scale parameters automatically…